
At a glance
- Holladay is a mature, tree-lined east bench city with a redeveloped village center, large lots and a quieter pace than the rest of the valley.
- Home prices are among the higher in Salt Lake County, with condos and townhomes near the village offering a path for downsizers.
- Holladay retirees pay Utah’s flat 4.45 percent income tax for 2026 like everyone else, and no estate tax, which matters when the house is the biggest asset.
- St. Mark’s Hospital is in the neighboring city, and Intermountain Medical Center and University of Utah Health are both close.
- Many Holladay retirees face the same decision: stay in a large home or move to the village. The plan should test both.
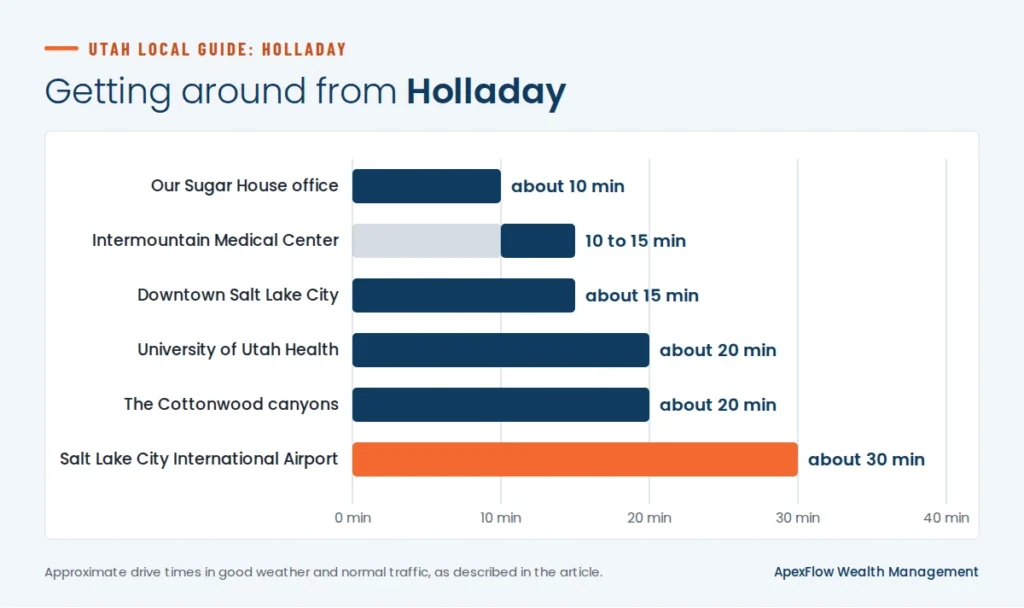
Holladay is one of the oldest settled parts of the Salt Lake Valley, and it shows in the best way: tall trees, Big Cottonwood Creek winding through, large lots and a village center that has been rebuilt around a town hall, restaurants and shops. It sits between Millcreek and Cottonwood Heights on the east bench, fifteen minutes from downtown and twenty from the canyons. Many of our clients have lived here for decades, and many others move here to retire near children on the east side.
Two minutesHow much of your retirement is actually decided?Get my Clarity ScoreBig lots and village condos
Holladay housing is largely single-family: mid-century ranches and ramblers on half-acre lots, larger homes along the creek and on the upper bench, and a growing number of condos and townhomes in and around Holladay Village. Prices are at the higher end of Salt Lake County, with lot size and trees commanding a premium. Downsizers often move from a large Holladay home to a village townhome and stay in the same community.
Utah property tax favors full-time residents, taxing a primary residence on 55 percent of its market value. Salt Lake County rates are moderate. A downsizing move within Holladay usually cuts the property tax bill, maintenance and utilities meaningfully. Groceries carry a reduced state sales tax rate, and everyday costs are in line with the rest of the east bench.
Mature homes carry mature maintenance: roofs, sewer lines, electrical and large yards that may need hired help. Earthquake insurance is a separate policy and worth pricing given the Wasatch Fault’s location along the east bench.
Taxes for Holladay retirees
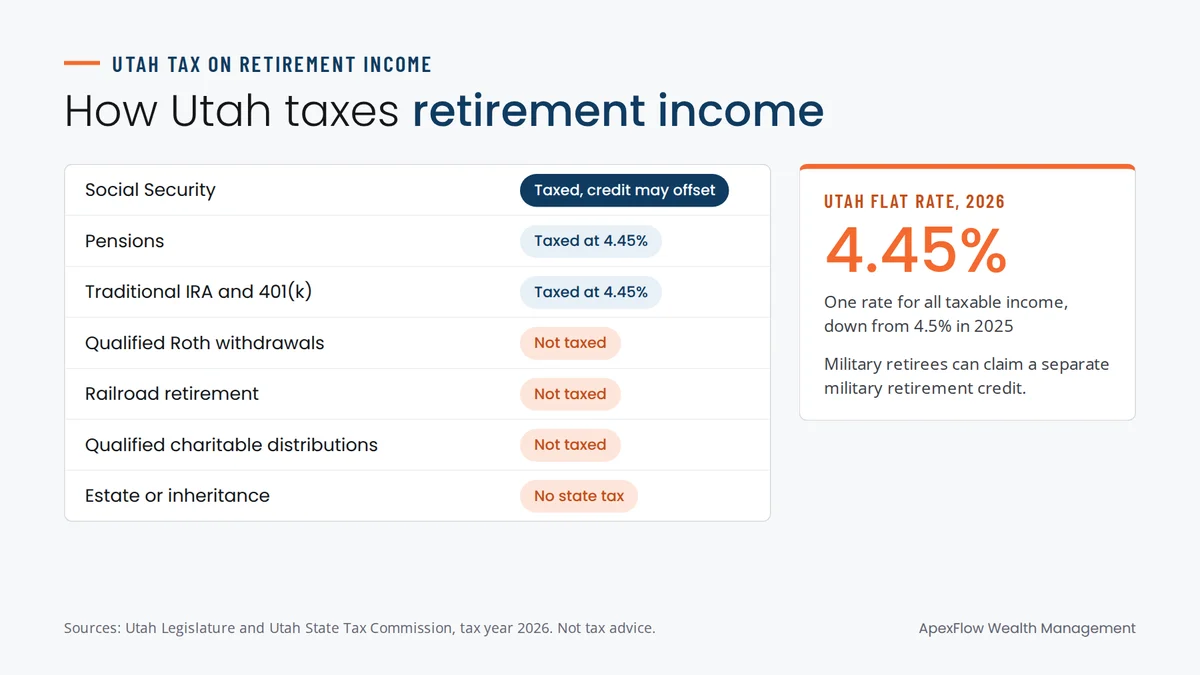
Holladay residents pay the same state income tax as everyone else in Utah, a flat 4.45 percent for 2026, on pensions, retirement account withdrawals and capital gains. Most retirees under the state’s income limit owe nothing on Social Security, and Utah has no estate tax, which matters for families planning to pass a valuable east bench home to the next generation. For the details, see how Utah taxes retirement income.
Care nearby
St. Mark’s Hospital, just across the border in Millcreek, is minutes from most of Holladay. Intermountain Medical Center in Murray is ten to fifteen minutes. University of Utah Health is twenty minutes north. Clinics from both major systems line Highland Drive and Holladay Boulevard. Traditional Medicare with a supplement covers all of them; Medicare Advantage plans should be checked for the specific providers you plan to use. Holladay also has a number of senior living and assisted living options, which matters if a long-term care plan may eventually involve a move within the community.
Village life
Holladay is quiet by design. The village has restaurants, a farmers market and events; Highland Drive and Fort Union offer the rest. The Cottonwood canyons are twenty minutes, downtown fifteen, the airport thirty. The bench sits high enough to avoid some of the worst winter inversion days. People move to Holladay and stay.
The decisions that matter most
Stay or downsize. The classic Holladay retirement question. A paid-off home worth a large share of your net worth is secure but illiquid. We model staying, with the maintenance and tax that come with it, against moving to a smaller home and investing the difference. Neither is always right.
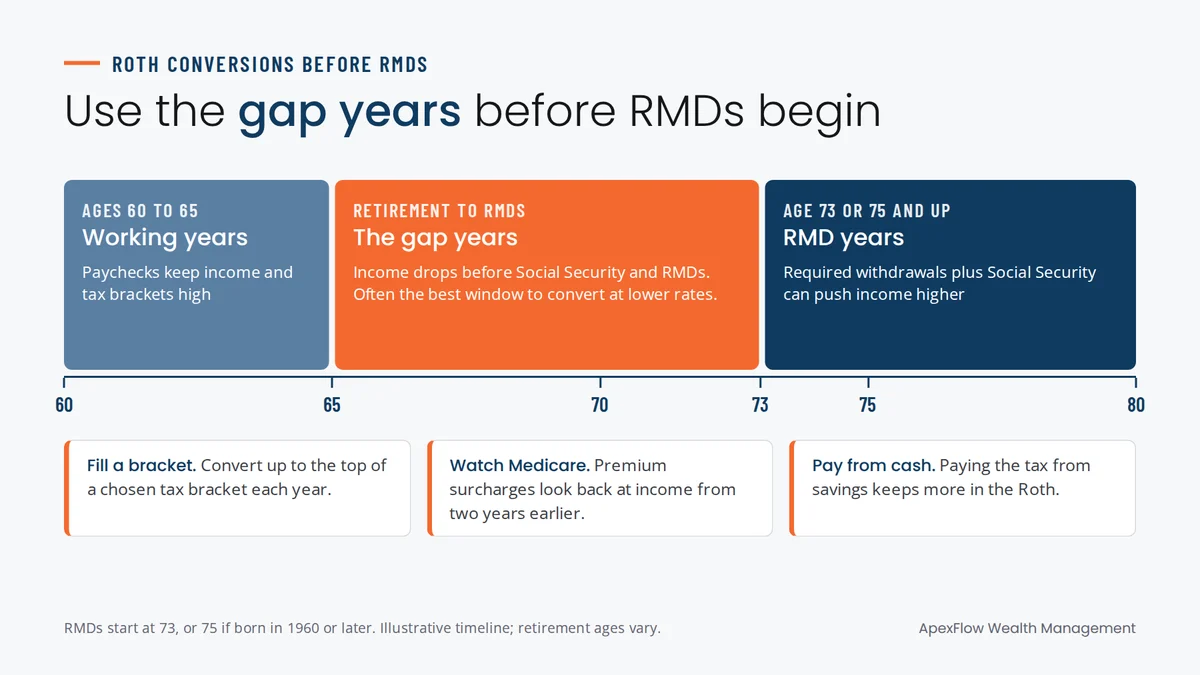
Income and tax sequencing. Social Security timing, pension options, withdrawal order and Roth conversions under Utah’s flat rate. See Roth conversions before RMDs.
Health and long-term care. Medicare choices, and a plan for care that may include insurance, self-funding or a hybrid policy. Holladay’s senior living options make a local plan realistic.
The home in the estate plan. A trust that holds the home avoids probate, and clear instructions about whether it is sold or kept prevent the most common family dispute. Our article on leaving a home to your kids without a fight covers it.
The investments. Keep enough in cash and bonds that the house never has to be sold on a deadline, and let the rest follow the plan. Our portfolio management page explains how we build that.
Hypothetical example: A widower, 72, has lived in a large Holladay home for forty years. It is paid off and worth roughly $1.4 million, more than half of his net worth. He is comfortable but the yard and the house are becoming work. We model a move to a village townhome: property tax and maintenance fall, roughly half the sale proceeds are invested, and his required minimum distributions are coordinated with qualified charitable distributions to his church. He keeps the same doctors and the same friends. The example is illustrative only.
Ten minutes from our office
Our office in Sugar House is ten minutes from Holladay Village. Many of our Holladay clients have been in their homes for decades, and the conversation often starts with the house and ends with everything else: income, taxes, care and what the kids will inherit. More on how we work is on our Salt Lake City financial planning page.
Frequently asked questions
For many people, yes: quiet streets, a village center, excellent hospital access and proximity to the canyons and downtown. It is among the more expensive parts of the valley, so the plan should start with the housing decision.
St. Mark’s Hospital in neighboring Millcreek is closest. Intermountain Medical Center in Murray and University of Utah Health are both within about twenty minutes.
Usually yes, through lower property tax, maintenance and utilities, and the proceeds can add meaningfully to the investment plan. Whether it is the right choice depends on your income plan and how you want to live.
Yes, at the flat rate of 4.45 percent for 2026. There is no general pension exclusion, though a small credit exists for those born before 1953 and a larger credit applies to Social Security for retirees under an income threshold.
Free one-page checklist
Moving to Utah: your financial checklist. Every step from before the move through your first year, on one printable page.
Talk it through with us
Every situation is a little different. If you want to talk through yours, book a 20-Minute Fit Call with one of our advisors, by video or in person. No prep and no obligation. Want to see how we work first? Start with the Purposeful Planning Process or our services.
The information in this article is general in nature and is not a recommendation for any individual. Consider your own circumstances or speak with an advisor before acting on it. Any opinions are those of the author and not necessarily those of Raymond James.
ApexFlow Wealth Management does not provide tax or legal advice. Please consult your tax or legal professional before acting on any strategy mentioned here.
Examples labeled as hypothetical are for illustration only. They are not based on any actual client and do not represent actual or expected results.
Related Articles
Dig deeper into our resource library
-
 October 29, 2026
How to Leave a Home to Your Kids Without Creating a Fight
The family home is the asset most likely to divide siblings after a death. Here is how to pass it on in a way that is clear, tax-smart and fair, with Utah-specific tools.Read more -
 November 5, 2026
Does Utah Tax Retirement Income? Social Security, Pensions and 401(k)s in 2026
If you’re planning to retire in Utah, or you already have, it’s worth knowing exactly how the state treats your income. The short answer: UtahRead more -
 November 5, 2026
Roth Conversions Before RMDs: Making the Most of the Gap Years
For many retirees, the years between leaving work and starting required minimum distributions are the lowest-tax years they’ll ever have. The paycheck has stopped, SocialRead more