
For decades, your budget had a built-in safety net: the next paycheck. Retirement changes that. Your income now comes from Social Security, maybe a pension, and the savings you spent a career building, and every dollar you spend is a dollar your portfolio has to replace. A retirement budget isn’t about restriction. It’s about knowing what your life actually costs, so you can spend on what matters with confidence instead of guilt.
At a glance
- Households 65 and older spent an average of $61,432 in 2024, about 22% less than the average household, but health care took a much bigger share.
- Split your retirement budget into essentials and wants, then try to cover essentials with reliable income like Social Security or a pension.
- Spending usually changes over retirement. Plan for an active early phase, a slower middle and higher health care costs later.
Why a retirement budget works differently
While you’re working, overspending one month usually gets corrected by the next paycheck. In retirement, overspending gets corrected by your portfolio, and withdrawals taken during a market decline are hard to win back. That’s why a retirement budget does two jobs at once. It tells you what you spend, and it tells you how much your savings need to produce each year.
It also changes over time. Many people spend more in the first few years of retirement, not less. In J.P. Morgan’s 2026 Guide to Retirement, 6 in 10 new retirees saw large swings in their spending during the first three years.
What retirees actually spend
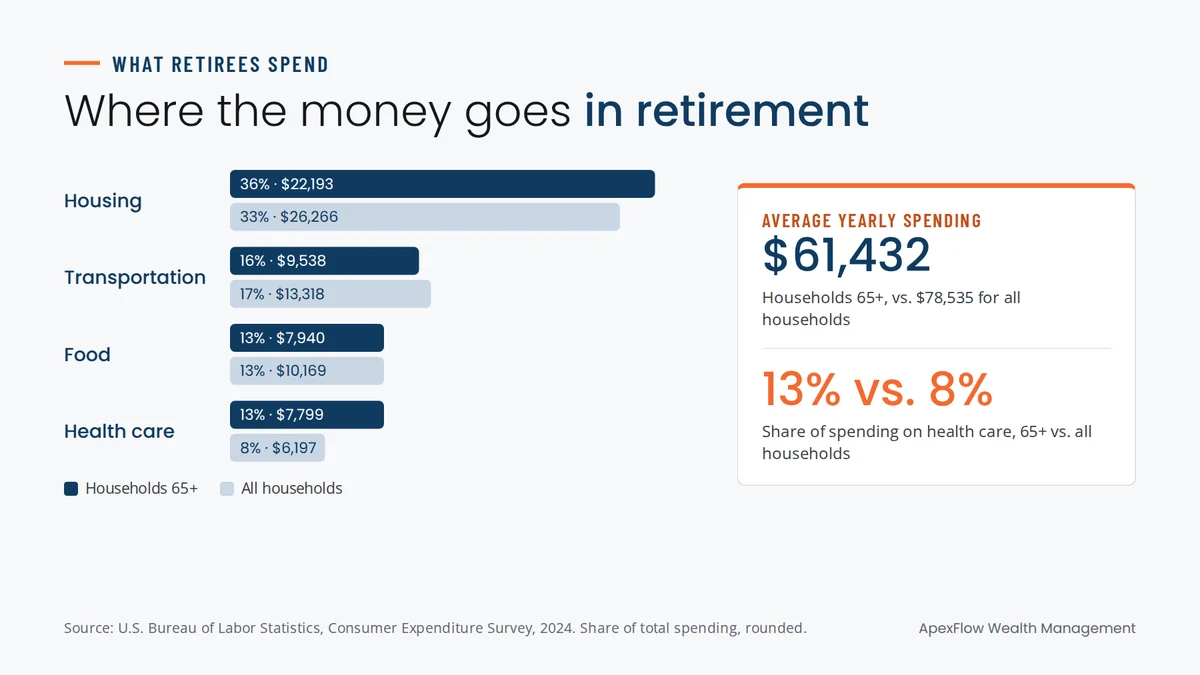
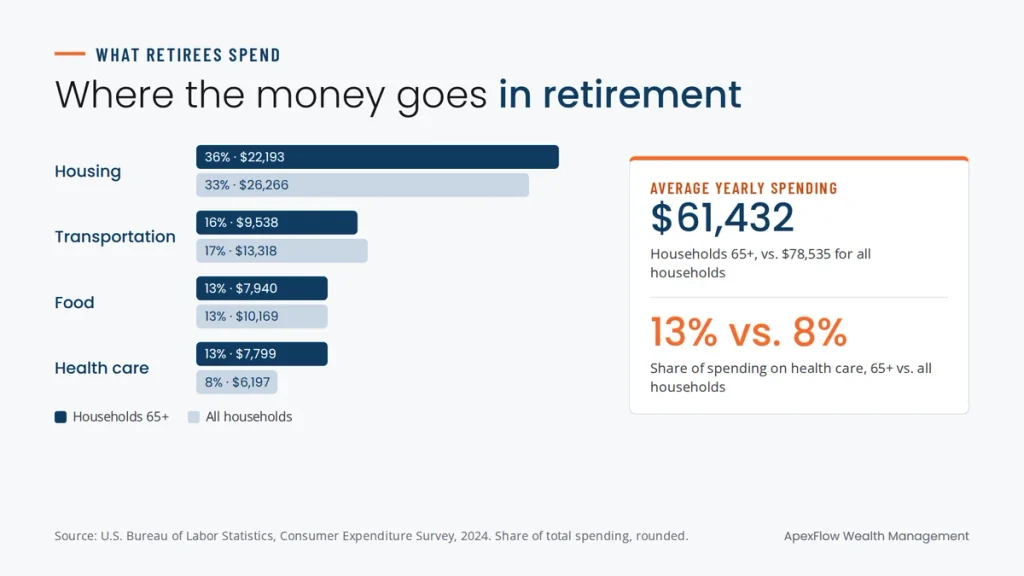
The U.S. Bureau of Labor Statistics tracks household spending every year. Here’s how households 65 and older compared with all households in 2024, the latest data available:
| Category | Households 65+ | Share of spending | All households | Share of spending |
|---|---|---|---|---|
| Housing | $22,193 | 36% | $26,266 | 33% |
| Transportation | $9,538 | 16% | $13,318 | 17% |
| Food | $7,940 | 13% | $10,169 | 13% |
| Health care | $7,799 | 13% | $6,197 | 8% |
| Total spending | $61,432 | $78,535 |
Source: U.S. Bureau of Labor Statistics, Consumer Expenditure Survey, 2024 data, via FRED. Shares are rounded.
Two things stand out. Retired households spend less overall, and health care takes a much larger share. Averages are just a starting point, though. Your budget should come from your own numbers.
Step 1: Start with what you really spend
Pull 12 months of bank and credit card statements and total them by category. A full year matters because so many costs are annual or irregular: insurance premiums, property taxes, holidays, travel and gifts. Most people find their real number is higher than their estimate, and it’s better to learn that now than three years into retirement.
Then adjust for what will change. Commuting, payroll taxes and retirement contributions usually go away. Travel, hobbies and health care often go up.
Step 2: Separate needs from wants
Divide your budget into two groups:
- Essentials: housing, utilities, food, insurance, health care, transportation, taxes and minimum debt payments
- Discretionary: travel, dining out, hobbies, gifts and helping family
This split is the heart of a durable retirement budget. Fidelity suggests trying to match essential expenses with guaranteed income sources such as Social Security, pensions and annuities. When your essentials are covered by income that doesn’t depend on the market, a down year means trimming a trip, not worrying about the mortgage.
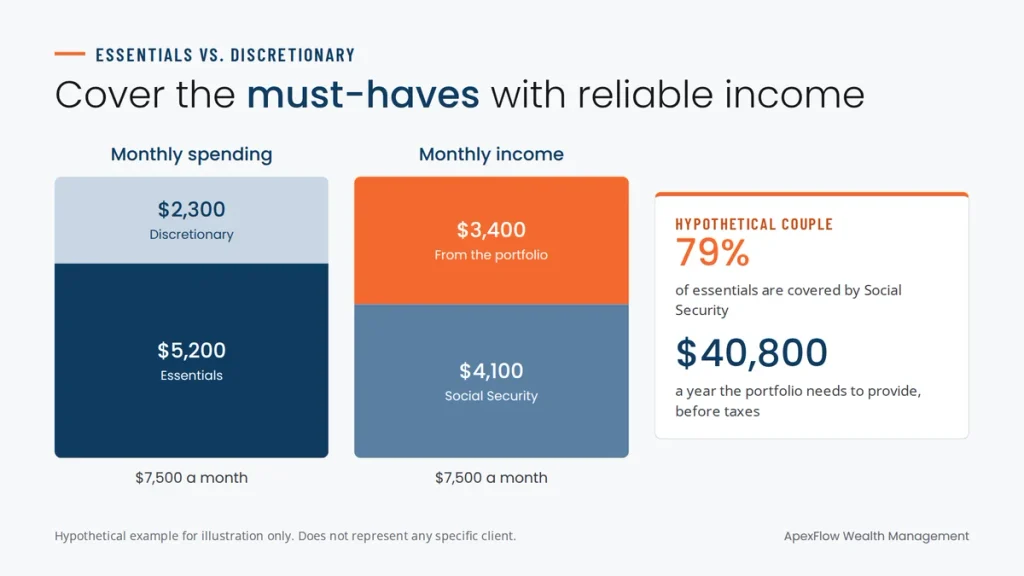
A hypothetical example. A retired couple spends $5,200 a month on essentials and $2,300 on discretionary items, $7,500 in total. Their combined Social Security is $4,100 a month, which covers about 79% of their essentials. Their portfolio needs to provide the remaining $3,400 a month, about $40,800 a year before taxes. Knowing that number tells them exactly what their savings need to do.
This example is hypothetical and for illustration only. It does not represent any specific client.
Step 3: Give health care its own line
Health care is the expense retirees most often underestimate. For 2026, the standard Medicare Part B premium is $202.90 a month per person, with a $283 annual deductible, according to CMS. Add supplemental coverage, Part D, dental, vision and out-of-pocket costs, and the total grows quickly.
Over a full retirement, Fidelity estimates a 65-year-old will spend about $185,500 on health care, not counting long-term care. Higher-income retirees can also pay more for Medicare through income-related surcharges, which is one reason taxes and health care planning go together. If you have a health savings account, it can help cover these costs tax-free. We explain how in Using Your HSA for Retirement.
Step 4: Plan for the phases of retirement
Retirement spending rarely stays flat. Many planners think of it in three phases:
- The active years. Travel, projects and new hobbies often push spending up early.
- The slower years. Spending on activities typically eases.
- The later years. Health care and support services take a larger share.
Research supports the pattern. EBRI found households aged 65 to 74 spent 22% less than those aged 50 to 64, and households 75 and older spent 23% less than those aged 65 to 74. The BLS data shows the same trend: households 75 and older spent $55,834 in 2024, compared with $65,354 for ages 65 to 74.
Building those phases into your plan can let you spend more confidently in the years you’re most likely to enjoy it.
Step 5: Save ahead for big, irregular costs
Some of the biggest retirement expenses don’t show up every month: a new car, a roof, a family wedding, a major trip, dental work. Estimate these, divide by the number of years until you’ll need them and set the money aside in a separate account. It keeps one large bill from turning into a large, poorly timed withdrawal.
Step 6: Count taxes as an expense
Withdrawals from traditional IRAs and 401(k)s are taxable income, and in Utah they’re taxed by the state too. Taxes belong in your budget like any other bill. Where your money comes from each year can change how much tax you pay. We cover the state side in Does Utah Tax Retirement Income? and one of the most useful planning tools in Roth Conversions Before RMDs.
Step 7: Turn your budget into a retirement paycheck
Once you know your number, set up a steady monthly transfer from your investments to checking, just like a paycheck. Keep a cash reserve covering the next year or two of planned withdrawals, so you’re not forced to sell investments in a downturn. We explain how much to keep in cash in Should You Move to Cash Before Retirement? and how bonds can fund the years after that in Bonds in Retirement.
How much income will you need?
Common guidance from the U.S. Department of Labor suggests you’ll need 70% to 90% of your pre-retirement income to maintain your standard of living. That’s a helpful starting point, but a budget built from your own spending is far more reliable than any rule of thumb. If you’re still a few years away, our 5 Years Before Retirement roadmap shows when to start this work.
Review it every year
A retirement budget isn’t something you build once. Revisit it each year: compare what you planned with what you spent, update for Social Security’s cost-of-living adjustment, and adjust for any changes in health, family or goals. Small, regular adjustments are much easier than large corrections later.
Where we fit in
At ApexFlow, we start with what you want your retirement to look like, then build the income plan to support it. That means mapping your spending, coordinating your income sources and tax strategy and stress-testing the plan against different markets. It all comes together in the Design stage of our planning process.
Frequently asked questions
Households 65 and older spent an average of $61,432 in 2024, according to the Bureau of Labor Statistics. Spending tends to be higher for ages 65 to 74 and lower after 75.
Essentials like housing, utilities, food, insurance, health care, transportation and taxes, plus discretionary spending like travel and gifts, and savings for irregular costs like cars and home repairs.
Start with Medicare premiums, which are $202.90 a month per person for Part B in 2026, plus supplemental coverage, prescriptions and out-of-pocket costs. Fidelity estimates lifetime retiree health care costs of about $185,500 for a 65-year-old.
For most households, yes, gradually. Spending is often higher in the first few years, eases in the middle years and shifts toward health care later.
Split your spending into essentials and wants, cover essentials with reliable income where possible, keep a cash reserve for near-term withdrawals and review your plan every year.
Talk it through with us
If you’re not sure what your retirement will really cost, or whether your savings can support it, that’s a great place to start a conversation. Book a 20-minute Fit Call. It’s virtual, no prep is needed and there’s no obligation.
With clarity and confidence,
Investing involves risk and you may incur a profit or loss regardless of strategy selected, including diversification and asset allocation. Raymond James and its advisors do not offer tax or legal advice. You should discuss any tax or legal matters with the appropriate professional.
Related Articles
Dig deeper into our resource library
-
 October 7, 2026
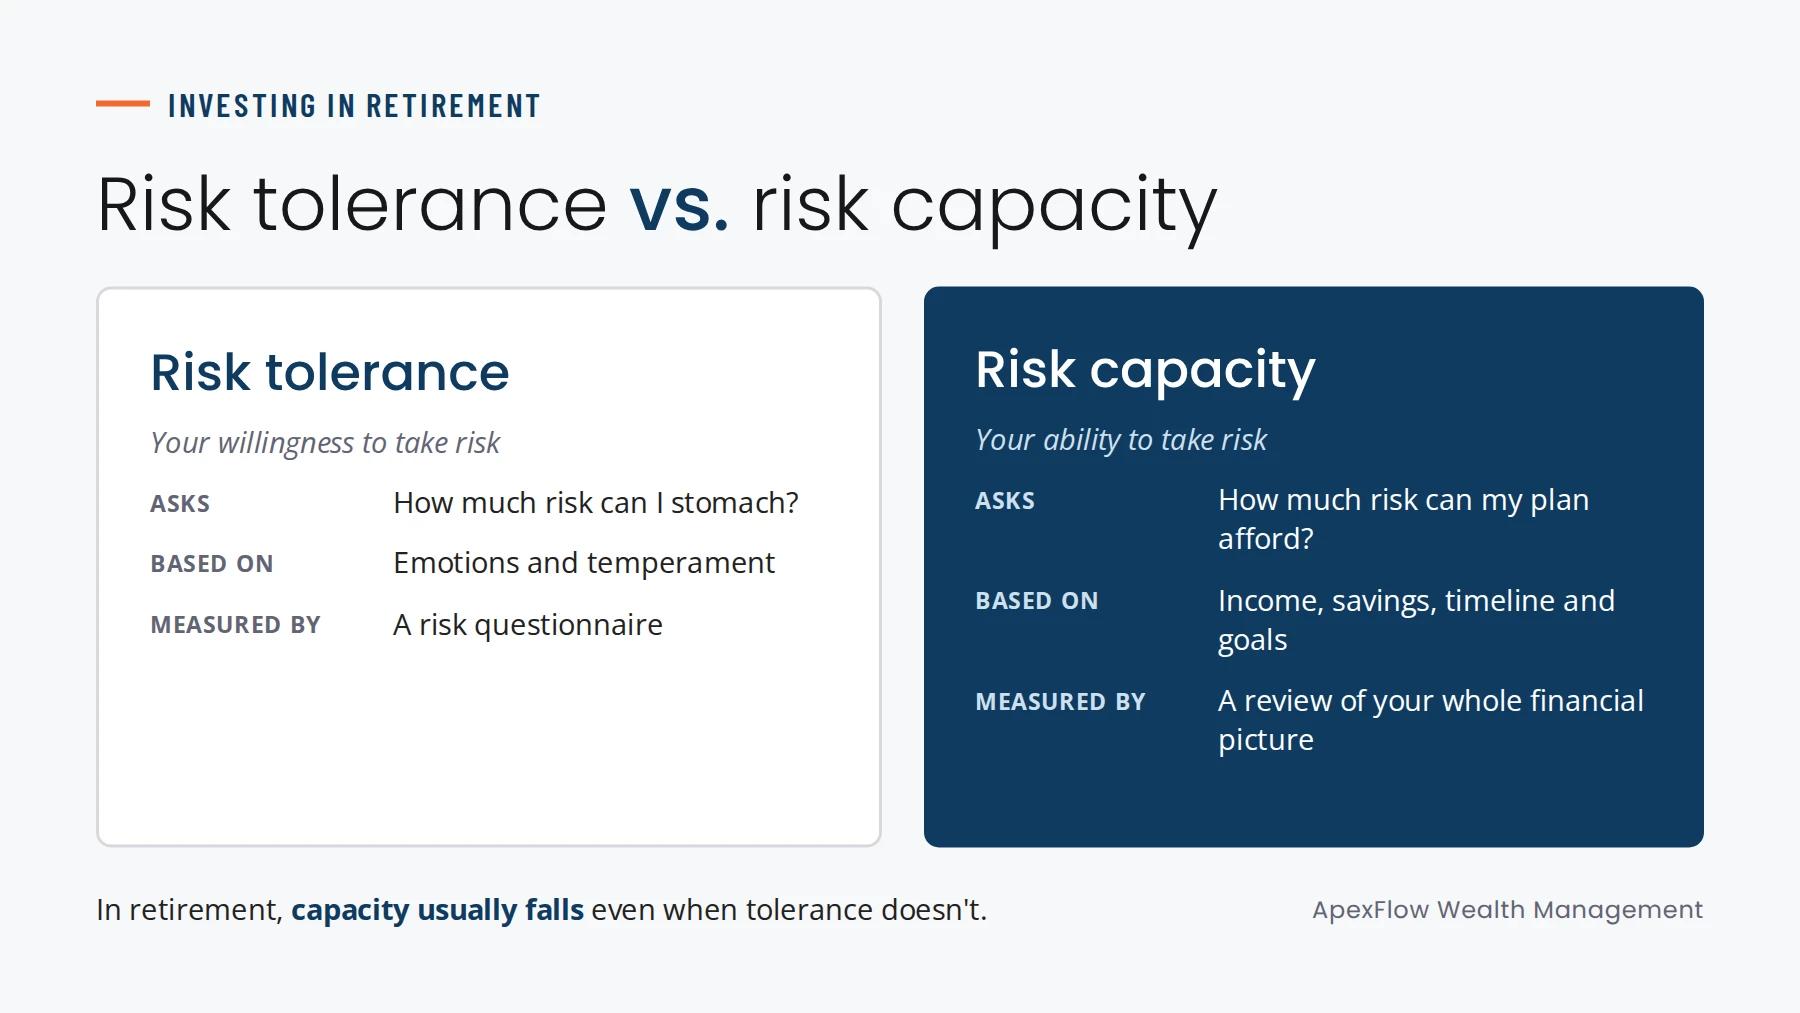
Risk Tolerance vs. Risk Capacity in Retirement
Ask most people about their investment risk and you’ll get an answer about how they feel. “I don’t like watching my account drop.” “I canRead more -
 October 7, 2026
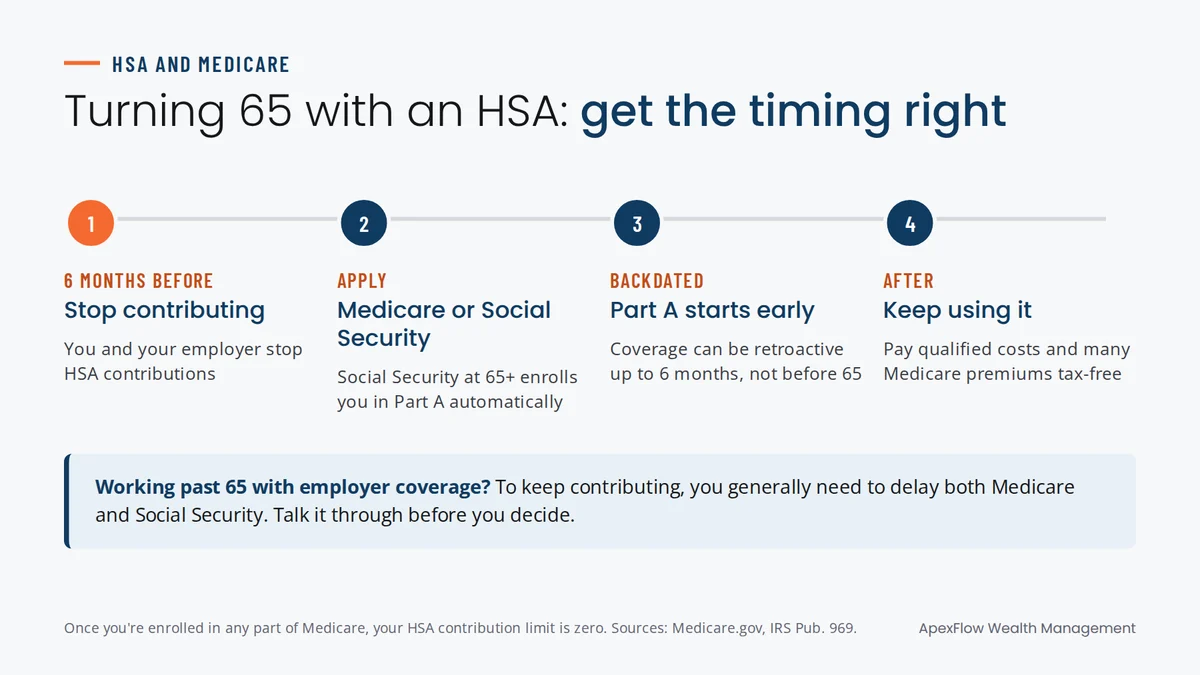
Using Your HSA for Retirement (and the Medicare Rule to Know)
Health care planning is one of the few areas of life where unpredictability isn’t the exception but the expectation. Costs shift, coverage evolves and importantRead more -
 October 7, 2026
Retirement Savings by Age: Why Business Owners Need a Different Yardstick
One of the most common questions people quietly carry is simple: “Am I on track for retirement?” For business owners, the usual answers rarely fit.Read more