
Most business owners have a will. Far fewer have answered the question that matters most for what they’ve built: what happens to the business itself if they’re suddenly not there to run it. For any company with more than one owner, the answer usually starts with a buy-sell agreement, and for every closely held business, it ends with a plan for who keeps the doors open on Monday morning.
At a glance
- A will decides who inherits your ownership stake. It doesn’t decide who runs the business, who can buy your share or how that purchase gets paid for.
- A buy-sell agreement sets the buyer, the price and the funding in advance, so a death, disability or departure doesn’t turn into a negotiation.
- An agreement only works if it’s funded, current and coordinated with your personal estate plan.
Why your will isn’t a business succession plan
It’s an easy gap to miss, because a personal will and a business succession plan feel like they should be the same conversation. They’re not. A will tells the world who inherits your ownership. It says almost nothing about who actually runs the company, how a transition gets funded or what happens to the employees and partners who were counting on you.
Say you own a business and something happens to you unexpectedly. Your will might name your spouse or your kids as the new owners. But owning a business and running one are very different skill sets, and your will has nothing to say about which one your heirs have.
Without a separate plan, a few things tend to happen at once:
- The business loses its most important relationships and know-how overnight.
- Surviving partners can end up legally tied to heirs who have no interest in, or ability to, run the company.
- The business, often a family’s largest asset, can lose value quickly at exactly the moment it needs to hold that value for the people inheriting it.
That last point is bigger than most owners realize. The Exit Planning Institute notes that a business typically makes up 80% or more of its owner’s total net worth.
What is a buy-sell agreement?
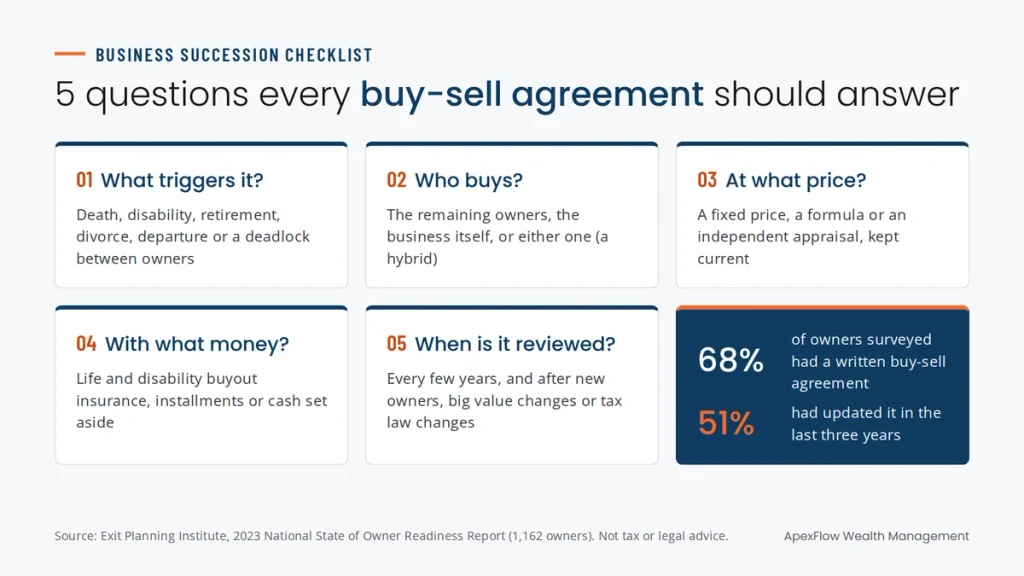
A buy-sell agreement, sometimes called a buyout agreement or business continuation agreement, is a legal contract between the owners of a business. Ideally drafted long before it’s needed, it spells out what happens to an owner’s share if they:
- Die
- Become disabled
- Retire or leave the business
- Divorce
- Can’t resolve a serious disagreement with the other owners
For each of those events, the agreement answers three questions: who has the right or obligation to buy the share, at what price and with what money. Settling those answers in advance removes the guesswork, and the potential for conflict, at the moment guesswork is most dangerous.
It also protects both sides. Your family gets a fair price and cash instead of a stake in a company they can’t control. Your partners keep control of the business without having to negotiate with your heirs.
Types of buy-sell agreements
There are two main structures, plus a hybrid that combines them.
| Cross-purchase agreement | Entity redemption agreement | |
|---|---|---|
| Who buys the departing owner’s share | The other owners, personally | The business itself |
| Who typically owns the life insurance | Each owner, on each other owner | The business, on each owner |
| Number of policies | Grows quickly as owners are added | One per owner |
| Tax considerations | Surviving owners generally get a higher cost basis in the shares they buy | Simpler to administer, but insurance proceeds can raise the company’s value for estate tax purposes (see below) |
| Often a fit for | Two or three owners | Businesses with more owners |
A hybrid, or “wait-and-see,” agreement lets the business and the remaining owners decide which one buys the share at the time it’s needed. That flexibility can help when it’s hard to predict which structure will make more sense years from now.
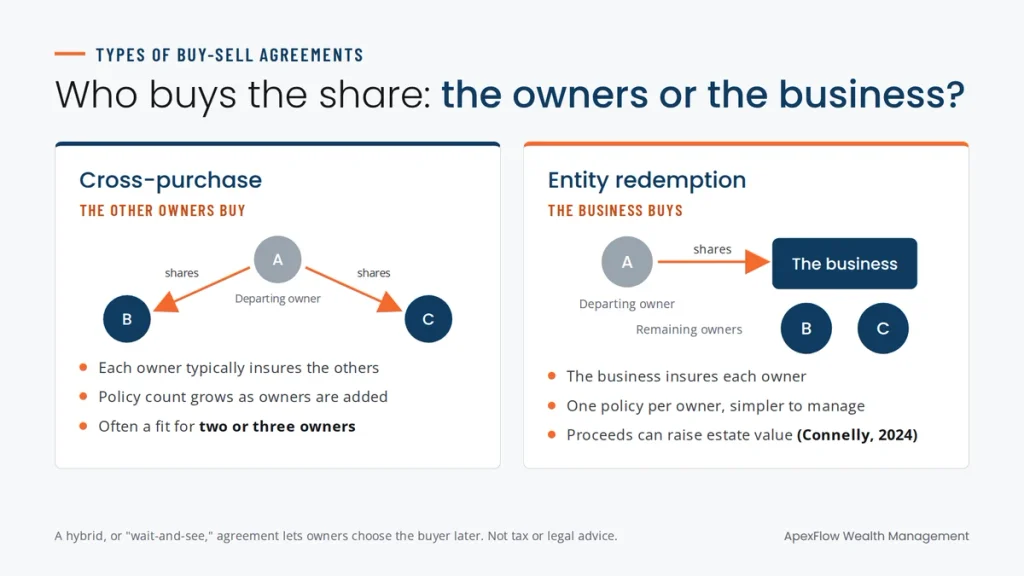
The right structure depends on how many owners there are, how the business is taxed, the owners’ ages and health and their personal estate plans. That’s a decision for your attorney and CPA to make with you, and it’s worth revisiting as the business changes.
How the price gets set
A buy-sell agreement is only as fair as the price it uses. Most agreements set value in one of three ways:
- A fixed price the owners agree on and update periodically. Simple, but it goes stale fast if no one updates it.
- A formula, such as a multiple of earnings or book value. Easier to keep current, but it may not reflect what the business is actually worth.
- An independent appraisal at the time of the triggering event. Usually the most accurate, though it takes more time and cost.
Whichever method you choose, revisit it. A price set ten years ago can leave your family underpaid, or leave your partners overpaying, at the worst possible time.
How to fund a buy-sell agreement
An agreement that promises to buy your share is only as good as the money behind it. Common ways to fund a buyout include:
- Life insurance, which provides cash when it’s most needed without draining operating capital or forcing a fire sale of business assets.
- Disability buyout insurance, which funds a purchase if an owner can no longer work. A long-term disability is often more likely than an early death, and it’s easy to overlook.
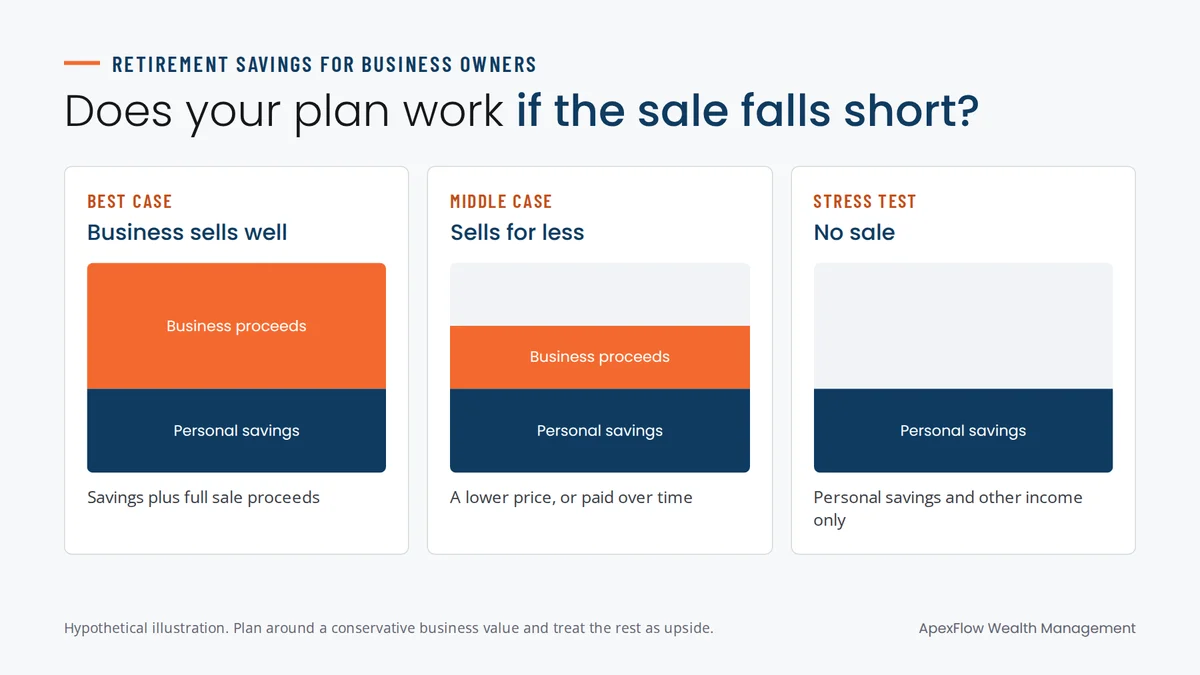
- Installment payments made over several years, often backed by a promissory note. These keep cash in the business, but they leave the seller’s family depending on the company’s future success.
- Cash or a sinking fund set aside inside the business over time.
Why the Connelly decision matters
In Connelly v. United States (2024), the U.S. Supreme Court ruled unanimously that life insurance proceeds a corporation receives to redeem a deceased owner’s shares count toward the company’s value for estate tax purposes. The company’s obligation to buy back the shares doesn’t offset them. In that case, the deceased owner’s estate was assessed $889,914 in additional estate tax.
The ruling doesn’t make entity redemption agreements wrong. It means that if your business uses corporate-owned life insurance to fund a buyout, it’s worth having your attorney and CPA review how the agreement is structured, especially if your estate could be large enough to owe estate tax.
Key person insurance: a different risk
Key person insurance (sometimes called key employee insurance) is separate from an ownership transfer. It addresses what happens to revenue and operations if a critical person becomes unable to work. That might be an owner, but it could just as easily be a top salesperson or the one engineer who knows how everything works.
The business owns the policy and receives the benefit, which gives it a financial bridge to recruit, retrain or reassure lenders and customers while it adjusts.
Build a business continuity plan
Beyond the legal and financial mechanics, every business needs a practical plan for the first few weeks after an owner is suddenly gone. A business continuity plan answers questions like:
- Who has authority to sign checks, approve payroll and make decisions?
- Where are the passwords, contracts, bank accounts and key documents?
- Who calls your most important clients, lenders and suppliers, and what do they say?
- Is there enough cash on hand to cover operations while ownership is sorted out?
- Who is being prepared to lead, and on what timeline?
The longer-term version of this, who’s being groomed to lead, when and how it’s communicated to family, partners and key employees, is your succession roadmap.
Three paths for your business, and why the choice matters
Passing the business to family only works if the next generation wants to run it and has been given the time and mentorship to be ready. Wanting to inherit a business and being prepared to run one are not the same thing, and confusing the two is one of the more common succession mistakes.
Selling to a co-owner, key employee or management team keeps continuity and know-how intact. But it requires a purchase the buyer can afford, often paid over time, which takes advance planning to fund.
Selling to an outside buyer can maximize the financial outcome for the owner. But it requires a business that’s truly sellable, meaning it doesn’t depend entirely on the owner to generate its value. That’s often a multi-year project to build toward, not something that can be arranged after the fact.
None of these paths is automatically better. The mistake is not choosing deliberately and letting the business drift into whichever path happens by accident.
Coordinate it with your personal estate plan
Business succession and personal estate planning have to be built together. If your will leaves the business to your kids but your buy-sell agreement gives your partner the right to buy them out, those two documents are working against each other.
A few places to check for conflicts:
- Who receives the sale proceeds. Should the money go to your spouse outright, or into a trust? Our post on wills vs. trusts explains the difference.
- Who owns the life insurance. How a policy is owned can affect both your estate tax picture and who controls the money.
- Fairness among your children. If one child takes over the business and another doesn’t, how will your estate plan treat them both fairly?
- Whether your family knows the plan. Even a well-drafted plan can cause conflict if it comes as a surprise. We make the case for having that talk in The Estate Planning Conversation Most Families Avoid.
If your company stock makes up most of what you own, the same concentration risk we describe in What Diversification Actually Means applies to you, too.
How often to review your buy-sell agreement
Plan on reviewing your agreement every few years, and any time something significant changes: a new owner, a big jump in the company’s value, a change in tax law, a divorce or a health change.
Many owners already have an agreement but haven’t kept it current. In the Exit Planning Institute’s 2023 national survey of 1,162 business owners, 68% said they had a written buy-sell agreement, but only 51% said theirs had been updated within the last three years.
Where we fit in
We don’t draft buy-sell agreements or legal documents ourselves. What we do is coordinate directly with your estate attorney, your accountant and your business advisors so your business succession plan and your personal estate plan are built to work together, not around each other.
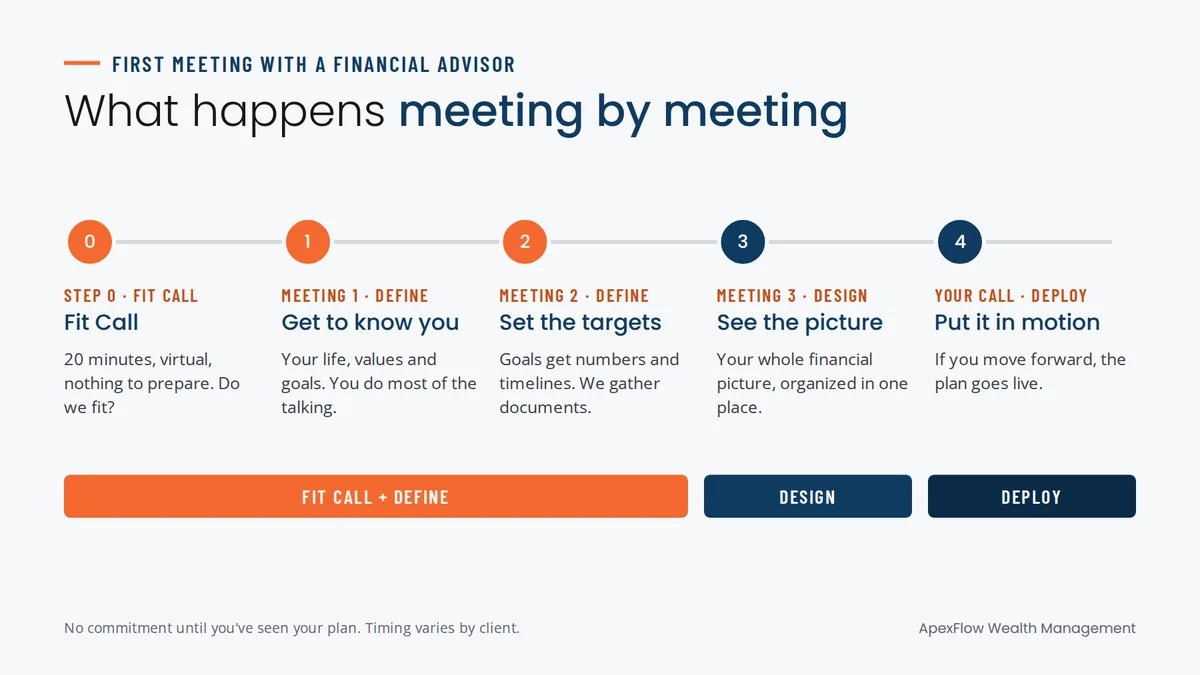
That includes looking at how the agreement is funded, what the payout would mean for your family’s income and how the business fits into your overall net worth. It happens in the Define and Design stages of our planning process.
Frequently asked questions
It’s a contract between business owners that decides, in advance, who can buy an owner’s share, at what price and with what money if that owner dies, becomes disabled, retires or leaves.
A traditional buyout agreement needs a buyer, so sole owners sometimes create one with a key employee or a competitor who agrees to buy the business. Even without one, a sole owner still needs a business continuity plan and an estate plan that says what happens to the company.
In a cross-purchase agreement, the remaining owners buy the departing owner’s share personally. In an entity redemption agreement, the business buys it. Each has different insurance, tax and administrative trade-offs.
Most are funded with life insurance and, ideally, disability buyout insurance. Some use installment payments or cash the business sets aside over time.
No. Buy-sell insurance pays for the purchase of an owner’s share. Key person insurance pays the business to help it absorb the loss of someone important to its revenue or operations.
Talk it through with us
If you’ve built something worth preserving for the next generation, the plan for who runs it next deserves the same intention you put into building it. Book a 20-minute Fit Call. It’s virtual, no prep is needed and there’s no obligation.
Investing involves risk and you may incur a profit or loss regardless of strategy selected, including diversification and asset allocation. Raymond James and its advisors do not offer tax or legal advice. You should discuss any tax or legal matters with the appropriate professional.
Related Articles
Dig deeper into our resource library
-
 October 7, 2026
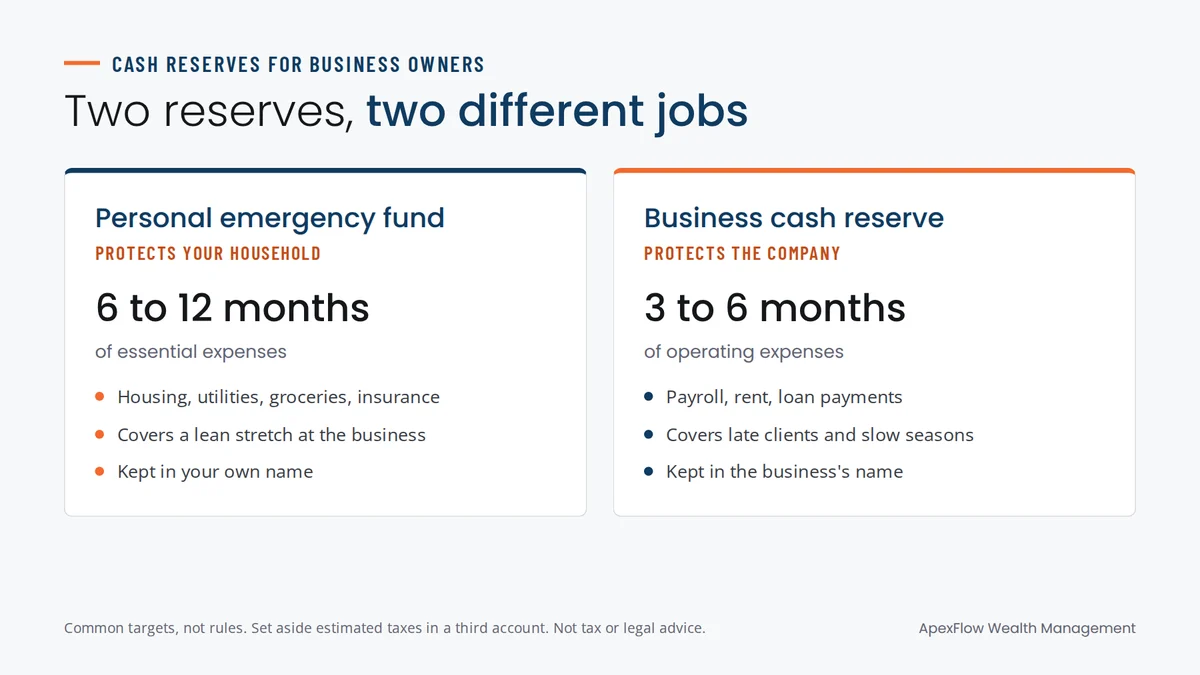
Cash Reserves for Business Owners: Personal vs. Business Emergency Funds
There’s a specific kind of anxiety that comes from not knowing your number. Not your net worth, not your retirement number, just the smaller, moreRead more -
 October 7, 2026
What to Expect in Your First Meetings With a Financial Advisor
Most people put off calling a financial advisor for the same reason they put off calling a doctor. It’s not that they don’t care. It’sRead more -
 October 7, 2026
Retirement Savings by Age: Why Business Owners Need a Different Yardstick
One of the most common questions people quietly carry is simple: “Am I on track for retirement?” For business owners, the usual answers rarely fit.Read more